OpenAI Cuts Its Own Valuation Target by $150B as the AI Funding Frenzy Cools
Nobody Would Take $1.4 Trillion, So OpenAI Cut Its Own Price by $150 Billion
OpenAI is close to completing a new financing round of up to $30 billion, but has trimmed its valuation target from an initial $1.4 trillion to $1.25 trillion.
From $1.4 Trillion to $1.25 Trillion: Where Did the Markdown Happen?
Three Valuation Anchors: $852B in March, $1.4T This Month, $1.25T at the End
In March, OpenAI completed a $122 billion financing at a post-money valuation of $852 billion, the only transaction this year with a clearly defined price. At the end of September, Bloomberg and Reuters both reported that OpenAI was seeking about $30 billion in new funding at a $1.4 trillion pre-money valuation. On October 23, Bloomberg, citing multiple people familiar with the matter, confirmed that negotiations were in their final stage and the valuation had been cut to $1.25 trillion.
Seven months separate the three anchors. The valuation jumped from $852 billion to $1.4 trillion, an increase of nearly 47 percent; then, in the final window before signing, $150 billion was cut, a drop of 11 percent. More precisely, this markdown happened after the subscription indication stage and before formal signing. Morgan Stanley and the San Francisco technology fund Dragoneer were pitching the round at the $1.4 trillion price to private wealth clients at the end of September. People familiar with the pitch process gave feedback that there was 'absolutely no rush to buy', and added that 'every previous time OpenAI came out it was frenzied; this time it is a bit flat'.
The $1.4 trillion quote sheet was sent out, and the other side only replied with 'read'.
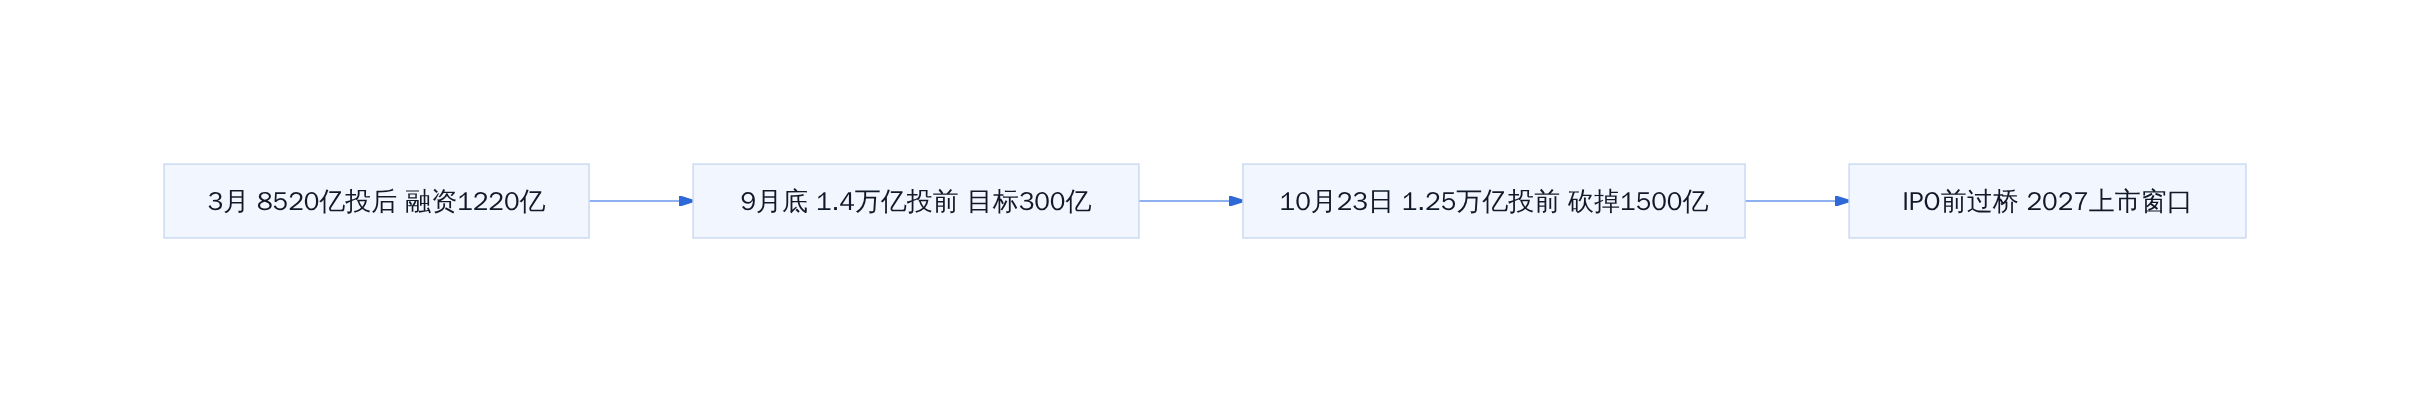
OpenAI's three valuation anchors in 2026
Where an 11 Percent Cut Sits Among Comparable Mega-Cap Deals
An 11 percent cut is not shocking as an absolute number, but in the context of this round it is different. Three constraints need to be read together. First, this is a pre-money valuation that does not include the new $30 billion raised in this round; after the new money comes in, the company is actually worth more, but the per-share stake held by old shareholders is diluted. Second, the lead investors are Coatue Management and a UAE sovereign fund, not secondary-market hedge funds; they are taking long-term positions rather than short-term arbitrage. Third, CFO Sarah Friar has explicitly positioned this round as a pre-IPO transition arrangement; in August she told employees that OpenAI 'will become a public company in 2027', though the exact date has not been set.
Between mega-cap rounds in the primary market, valuations are usually monotonically increasing. Investors rush in at a premium, and issuers rarely cut the price voluntarily in the final stage of negotiation. To widen the frame: over the past three years, private SaaS deals at the ten-billion-dollar scale and above have typically seen pullbacks of less than 5 percent, and almost all of those happened in the quiet period before the next round, not in the last week before signing. OpenAI adjusted the price this time after indications of interest were already in hand, equivalent to buyers coming back with letters of intent to ask whether it could be cheaper. A one-time 11 percent cut, made after subscriptions, means the demand-side contraction exceeded the issuer's expected model.
What is more striking is that this markdown was not the result of one buyer squeezing the price; the entire demand side weakened at the same time. During the same period, US tech stocks faced sustained selling, and mixed earnings from Meta and Tesla deepened doubts about whether the debt-driven AI infrastructure boom can continue. OpenAI itself told investors in February that its target is about $600 billion in total computing spending by 2030, and that number is still on the wall. The $1.25 trillion pre-money valuation corresponds to old equity; the new money has not arrived yet, and the bill for compute purchases is already counting down.
The most direct lesson for practitioners from this markdown: as the AI infrastructure capex cycle for the first time lags behind the valuation cycle, pricing power shifts from seller to buyer. If you have a project dependent on large GPU or electricity purchases, the window for negotiating with upstream suppliers is better than it was three months ago. But the boundary needs to be kept in mind: Anthropic will list in mid-November with a target valuation of $1.5 trillion to $2 trillion. Once it opens a secondary-market pricing anchor, the coordinate system of the entire track will be recalibrated; negotiating at that point will no longer be the same market.
Who Is Taking the Round, Who Is Watching
The Lead-Logic of Coatue and the UAE Sovereign Fund
Coatue is a New York technology-focused fund that has been involved in early rounds of Meta and SpaceX. This time it is not carrying the round alone; it has brought in a UAE sovereign fund as co-lead. Frankly, this is not purely financial-return logic. OpenAI is simultaneously negotiating a commercial agreement whose core is priority purchase rights for compute capacity newly built by UAE partners. For a sovereign fund, what is being bought is not just an equity certificate, but eligibility to use an entire set of compute infrastructure. In OpenAI's internal plan for $600 billion in computing spending by 2030, UAE data centers are a piece of the puzzle that cannot be filled elsewhere.
The Real Temperature of the Morgan Stanley and Dragoneer Pitch
The Financial Times quoted a person familiar with the pitch process as saying 'there was absolutely no rush to buy'. The same person added: 'Every previous time OpenAI appeared it was frenzied; this time it is somewhat silent.' When Morgan Stanley and Dragoneer handed the $1.4 trillion pre-money valuation to private wealth clients, the backdrop was mixed earnings from Meta and Tesla and collective market doubt about whether the debt-driven AI infrastructure boom can continue. Wall Street has gone from scrambling to take deals to starting to pick and choose.
Anatomy of the $30 Billion Bridge Financing
Pre-Money Definition: Why $1.25 Trillion Does Not Include the New $30 Billion
$1.25 trillion is the pre-money valuation. After the $30 billion comes in, the effective post-money valuation is $1.55 trillion. This choice of definition is not an accounting trick; it is about the allocation of benefits: new funds are not put into the numerator, so the dilution rate for existing shareholders (SoftBank, Microsoft, etc.) is lower, and the entry price for Coatue and the UAE sovereign fund also looks restrained. When reading mega-cap private deals, the first step is to confirm whether it is pre-money or post-money; at the $30 billion scale, the gap between the two is 24 percent.
Alignment with the 2027 IPO Timeline
CFO Sarah Friar told employees in August that the company would go public in 2027. In June, OpenAI confidentially submitted a prospectus to the SEC, but no specific date was disclosed. This round is positioned as a 'bridge', not as final pricing. Competitor Anthropic has a target of $1.5 trillion to $2 trillion and plans to list in November. OpenAI must still have an independent narrative after Anthropic goes public; otherwise secondary pricing could push this round's anchor downward.
What the Supporting Compute Agreement Means: Priority Purchase Rights for New UAE Compute
Beyond the financing, OpenAI is also negotiating a commercial agreement to obtain priority purchase rights for compute capacity newly built by UAE partners. The background is that OpenAI has told investors it expects about $600 billion in total compute spending by 2030. Priority purchase rights turn part of the capex from immediate cash outflow into locked supply, making the pace smoother, but the premise is that construction on the UAE side does not fall behind. Practitioners who make AI infrastructure budgets can directly reference this structure: use long-term contracts and priority rights instead of spot procurement, and align the capex cadence with the financing cadence, not the other way around.
Two Actionable Judgments for Practitioners
For AI Infrastructure Investors: How to Hedge the Valuation Risk of Debt-Driven Capex
OpenAI has committed to about $600 billion in compute spending before 2030, while current annualized revenue is still at the tens-of-billions scale. The gap is filled by continuously raising funds in the primary market at expansion multiples. This round's 11 percent cut is the first clear signal that expansion multiples are narrowing.
If you manage an AI infrastructure fund, one thing to do now is run a stress test on every company in the portfolio: after a 30 percent to 40 percent capex cut, does the compute roadmap still hold? If the answer is no, the entry multiple should be pushed down. A bridge structure is essentially paying for the gap between 'model compute demand' and 'revenue carrying capacity'; the contract should clearly state the exit path and time-trigger conditions if the IPO does not happen.
For Those Watching Primary-Market Liquidity: From 'Frenzy' to 'Silence', Which Leading Indicators to Read
The March round's pitch feedback was 'every time OpenAI appears, there is frenzied buying'; the October round has become 'no rush at all'. The same target; within five months, buy-side temperature has fallen from above the freezing point to the freezing point.
When reading leading indicators, watch three things. First, the resonance between secondary-market discounts and public-market moves: if marks for AI private targets on Forge and Caplight are also weakening over the same period, this is not a single event; the entire liquidity curve is contracting. Second, the compression of the deal cycle: OpenAI gave this round a hard deadline of October 30, and bargaining power has already moved from buyer to seller. Third, the change in lead-investor structure: in March, sovereign funds followed US tech funds into the deal; this time, a UAE sovereign fund and Coatue are co-leads, and the layer bearing risk has changed.
There is also an external variable: Anthropic's mid-November IPO at a target valuation of $1.5 trillion to $2 trillion. If that pricing is weak, the entire private AI valuation anchor will be dragged down another notch, and OpenAI's bridge structure will turn from a 'transition arrangement' into 'passive dilution'.
References
- IT Home: Report says OpenAI financing negotiations are in their final stage, valuation target lowered to $1.25 trillion
- CNBC video: OpenAI nears funding round of up to $30B at a $1.25T valuation
- Wallstreetcn: Investors not buying it? OpenAI lowers valuation target to $1.25 trillion
- The Decoder: OpenAI lowers valuation target, raises up to $30 billion
- Reuters: OpenAI targets $30 billion funding at $1.4 trillion valuation
- Anue: OpenAI reportedly advances $30 billion in new financing, Wall Street no longer rushing to buy
Extended Entries
- Original archive: https://tobemagic.github.io/ai-magician-blog/posts/2026/10/24/14万亿没人接openai自己把价砍了1500亿/
- Official account: Computer Magician